
Loan broker CRM
The loan broker CRM that places the deal too
Track every borrower, fill every application and keep 100% of your commission.
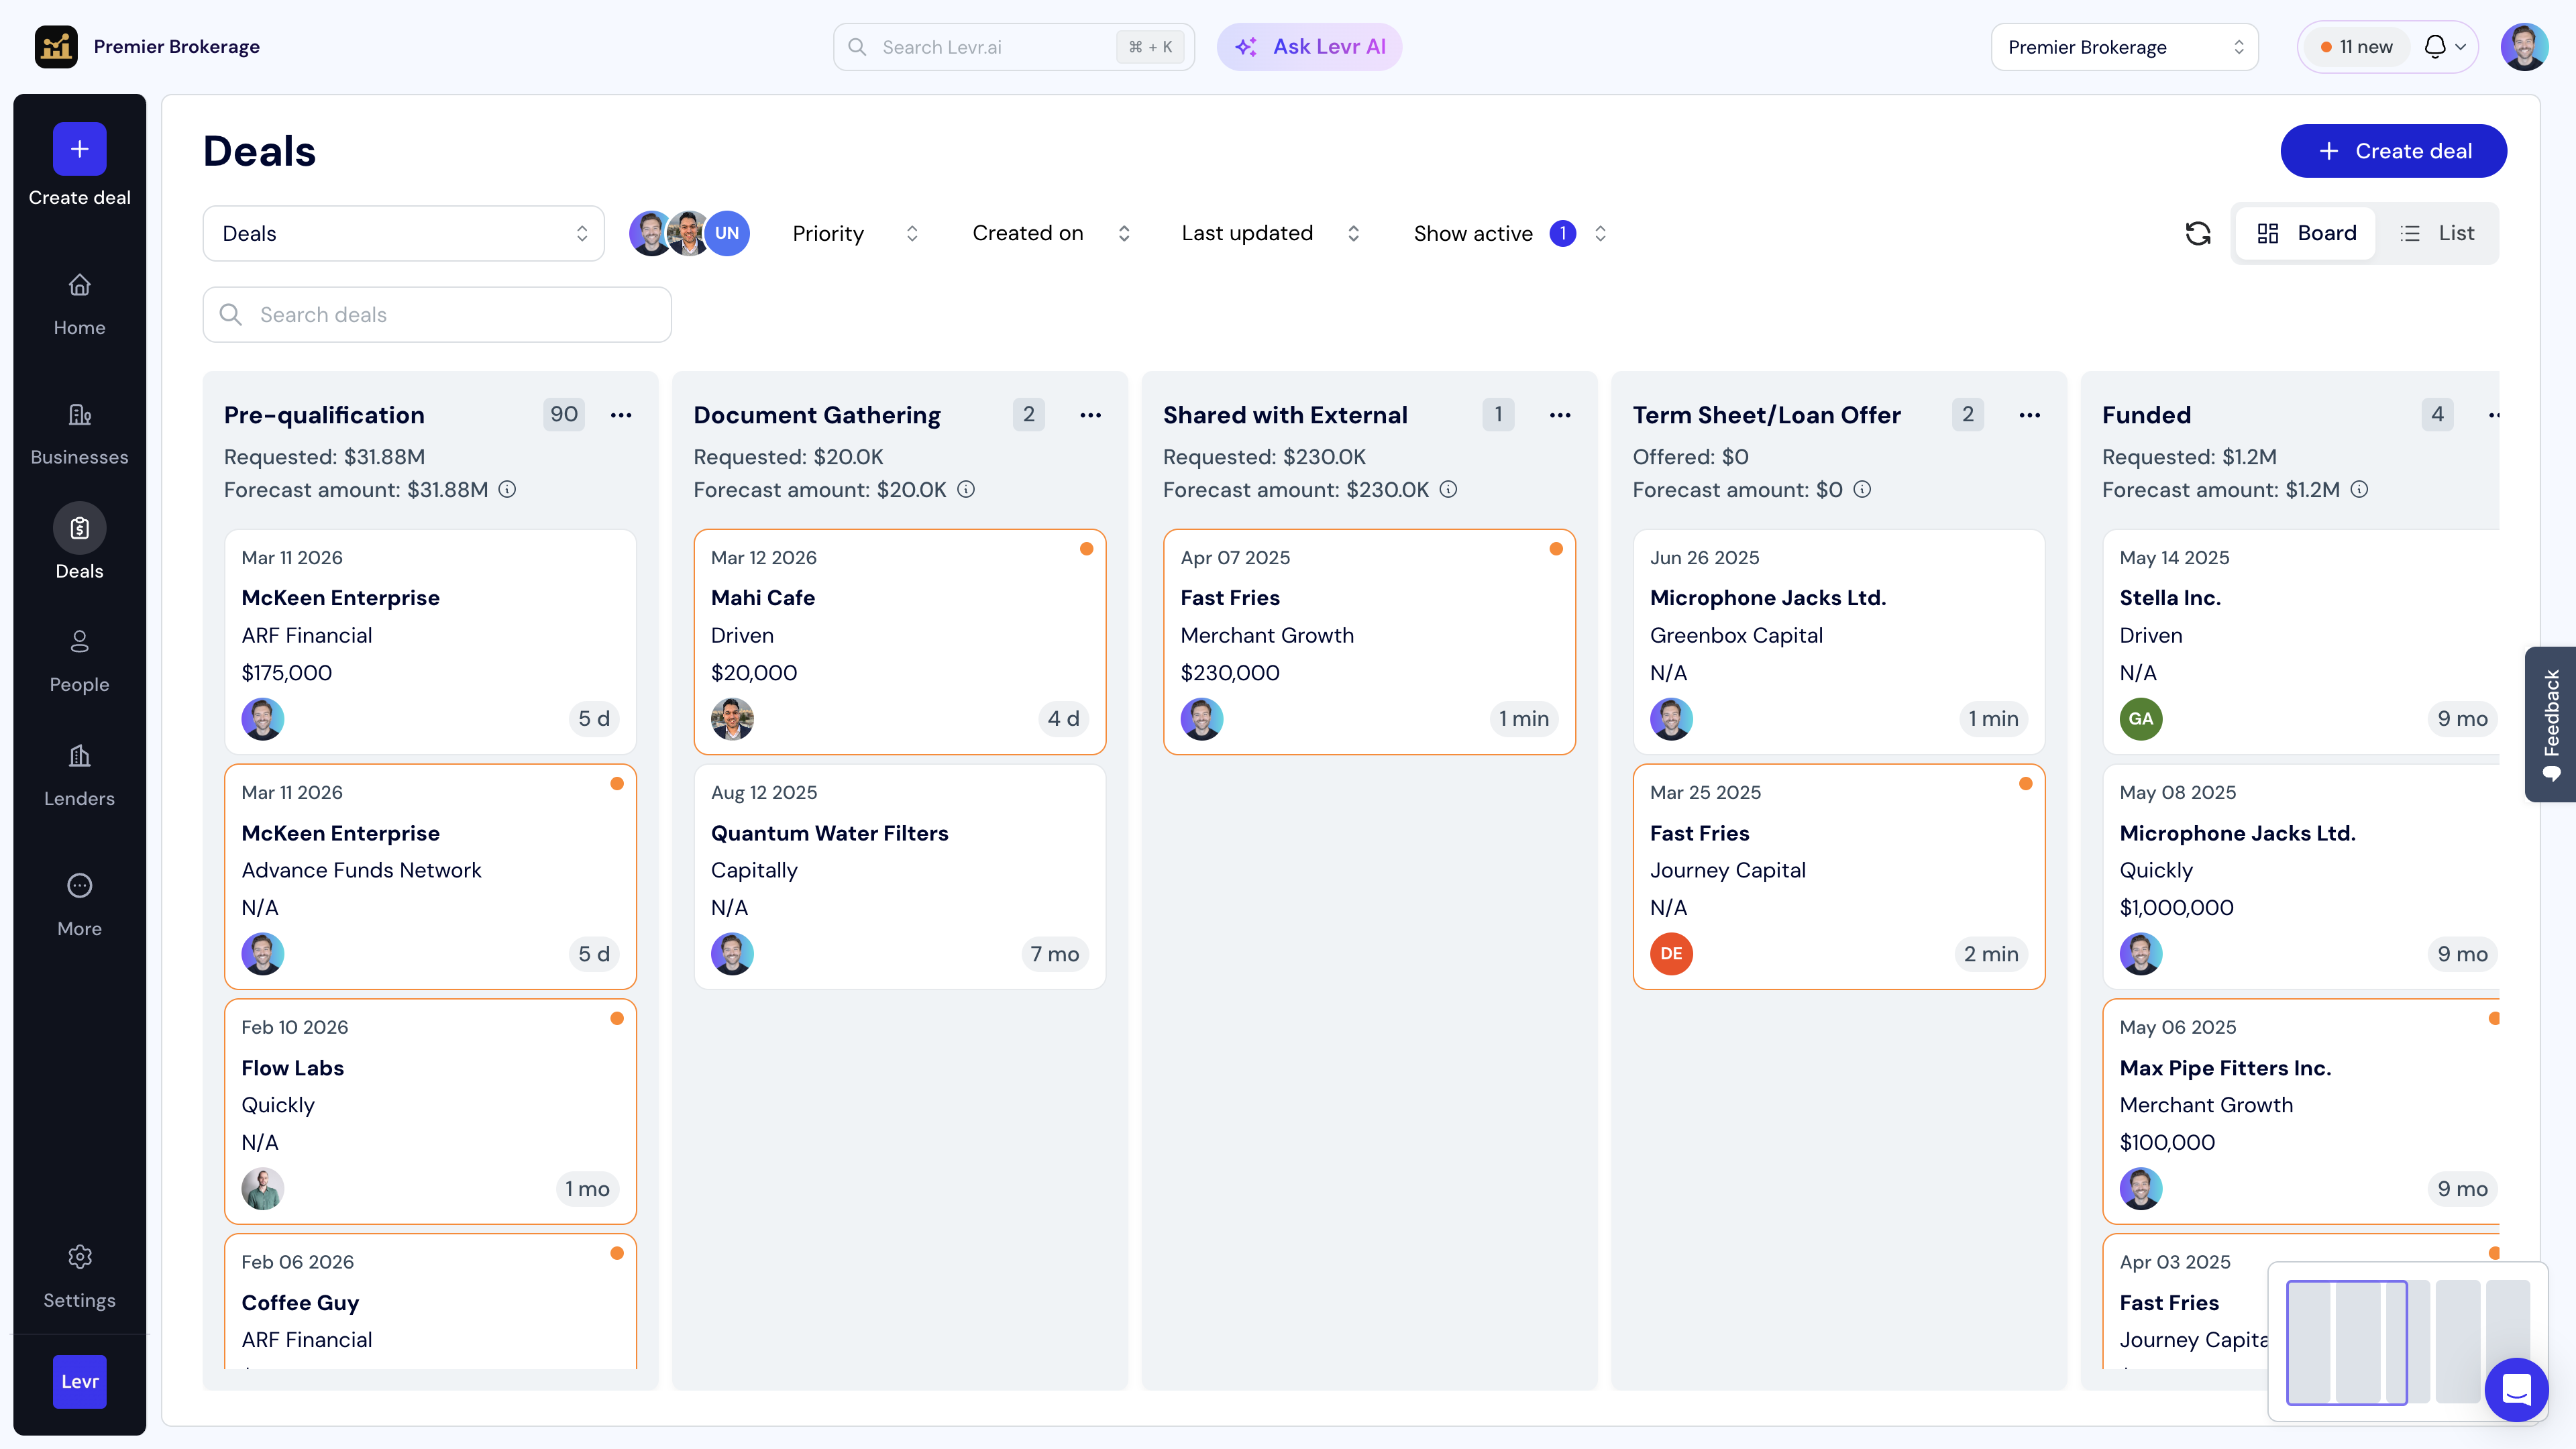
A loan broker CRM is the record of every borrower, deal and lender conversation in your brokerage. A business loan broker CRM should go further than contacts and stages: it should hold the documents, build the application, show which lenders fit, send the submission and record what you earn when the deal funds.
What should a loan broker CRM track?
It should track four things: the borrower, the file, the lenders and the money. Miss one and the deal leaks out of your system into email threads and spreadsheets.
The borrower
Who they are, what they need, how much and for what, and where they came from.
The file
Bank statements, tax returns, ID and the completed application, all attached to the deal.
The lenders
Who the deal went to, what came back, and which lender is waiting on what.
The money
Funded amount, expected commission and what has actually been paid.
A sales CRM was built for the first one. Brokers make their money on the other three, which is why so many end up with a CRM on one screen and the real work on five others.
Ask one question of any CRM you trial: can it take a borrower from first contact to a lender submission without you retyping a single field? If the answer is no, you are paying for a contact list.
Why does a generic CRM fall short for loan brokers?
A generic CRM stops at the contact record, while a loan broker earns on the application, the lender match and the funded deal. This table shows the gap.
| What a broker needs | Generic sales CRM | Levr |
|---|---|---|
| Borrower documents | Generic sales CRMFile attachments with no idea what is inside them. | LevrClients or brokers drop in documents and Levr parses them and fills out the application. |
| Lender fit | Generic sales CRMCustom fields you maintain by hand. | LevrLender matching across every loan type, plus the lenders you add yourself. |
| Submissions | Generic sales CRMEmail from your inbox, then log it manually. | LevrSubmit from the deal, with lender communication kept on the same record. |
| New business | Generic sales CRMImport lists you bought somewhere else. | LevrAI lead finder, plus an Apply Now button on your site under your own brand. |
| Commission | Generic sales CRMA deal value field. | LevrCommission tracking on every deal, and no platform split of what you earn. |
| Cost | Generic sales CRMPer seat, per month. | Levr$0 for brokers. |
How does Levr compare with Centrex as a business loan broker CRM?
Both are built for business lending, and the right pick depends on whether you broker deals only or also lend, service loans or manage investors. Centrex describes a business-loan CRM for brokers, direct lenders and investors, with multi-lender submissions, electronic signatures, a client portal and loan servicing, and it lets brokers add any lender. That breadth is a real strength for a shop that funds or services its own loans.
Levr is focused on the broker: finding borrowers, building the file, matching lenders, submitting and getting paid, at $0 with no split of your commission. Centrex does not publish a standard price on the product page we reviewed, so ask for a quote, and ask to see one live deal go from application to lender submission during the demo itself. The full breakdown is in Levr vs Centrex.
How does a CRM for business loan brokers fill the pipeline?
It should bring in new borrowers, not just store the ones you already have. Levr does this two ways.
- Outbound. The AI lead finder researches businesses that match the brief you give it and shows the public sources behind each one, so you call prospects with a reason to talk.
- Inbound. White label business lending puts an Apply Now button on your website under your brand and domain. Every borrower who applies becomes a deal in your CRM with their documents attached.
That changes what the CRM is worth. A contact database only grows when you type into it. A CRM that prospects and takes applications grows every time a borrower lands on your website.
For the channels that work best, read our guide to business loan leads.
What happens to your pipeline when the CRM does the paperwork?
More deals reach a lender, because the application is filled from the borrower’s documents instead of retyped.
Click play to see a deal created and sent to matched lenders.
What does a loan broker CRM change for a growing brokerage?
It turns a busy pipeline into funded volume you can see and count. For a broker writing term loans, lines of credit, equipment and SBA deals, that shows up in a few places.
From pipeline to paid
Every deal has a stage and a next step, so no borrower goes quiet because nobody owned the call.
Levr has a lender for every loan type, from prime SBA lending to MCA and revenue based finance, so a decline is a rematch, not a lost client.
Funded deals and expected commission sit on the same record as the borrower.
Your brand stays front and center the whole way. The borrower sees your portal and your Apply Now button, and the client relationship stays yours. When a client comes back for a business line of credit after a term loan, their file is already there.
Plenty of shops live by one rule: if it is not in the CRM, it did not happen. That rule only sticks when the CRM is also where the work gets done, which is why intake, submissions and commission belong on the same record.
You can also run the CRM from the AI assistant you already use. The Levr MCP server connects Claude or ChatGPT to your workspace so it can find lender matches, complete applications and move deals forward, and there is an API for your own tools. See pricing: it is $0.
A broker’s experience with Levr
“It is like a CRM and LOS all together. It consolidates the tools I had mishmashed together in Trello and Asana.”
What do brokers ask about loan broker CRMs?
Quick answers to the common ones.
Is the Levr CRM free?
Yes. The broker plan is $0, with no per seat fees and no platform split of lender-paid commissions.
Can I bring my existing lenders into the CRM?
Yes. Add your own lenders and record your terms, and they stay private to your account.
Will my borrowers see the Levr name?
Your client portal and Apply Now button carry your brand and sit on your domain, so borrowers deal with you.
Can borrowers upload their own documents?
Yes. They upload through your branded portal, and Levr parses what they send and fills out the application.
Does it handle SBA and equipment deals, not just MCA?
Yes. Levr covers every loan type, so one CRM holds your term loans, lines of credit, equipment, SBA and MCA deals.
Do I still need a separate CRM?
Most brokers do not. Levr keeps the borrower, the documents, the lenders and the commission on one record.
Which guide should you read next?
Go deeper on the part of the workflow you care about most.
Ready to turn your pipeline into funded deals?
It costs nothing to start. Open a free account and load one live borrower.